“The money was not capital, under the circumstances, because it could not be used to produce anything.” — David A. Wells, Robinson Crusoe’s Money
Investors have an understandable obsession with interest rates. 7% is better than 10%. 10% is better than 12%. And 12% is certainly better than 15%. It’s just math, right? Except when it isn’t.
One of the most expensive mistakes investors make is focusing on the price of money while ignoring the cost of not having it.
I’ve spent most of my professional life looking at investments through two lenses: highest and best use and opportunity cost. Both apply particularly well to real estate—and especially to private or bridge financing.
Sometimes expensive money is actually cheap. And sometimes cheap money is extraordinarily costly.
Price is not the same thing as cost
Suppose you find a property worth $1 million after stabilization that you can buy today for $700,000. The catch: the seller wants to close in 10 days, the property needs work, and the financials are messy. Maybe there are vacancies, deferred maintenance, an unfinished renovation or some other wrinkle that makes a conventional lender uncomfortable.
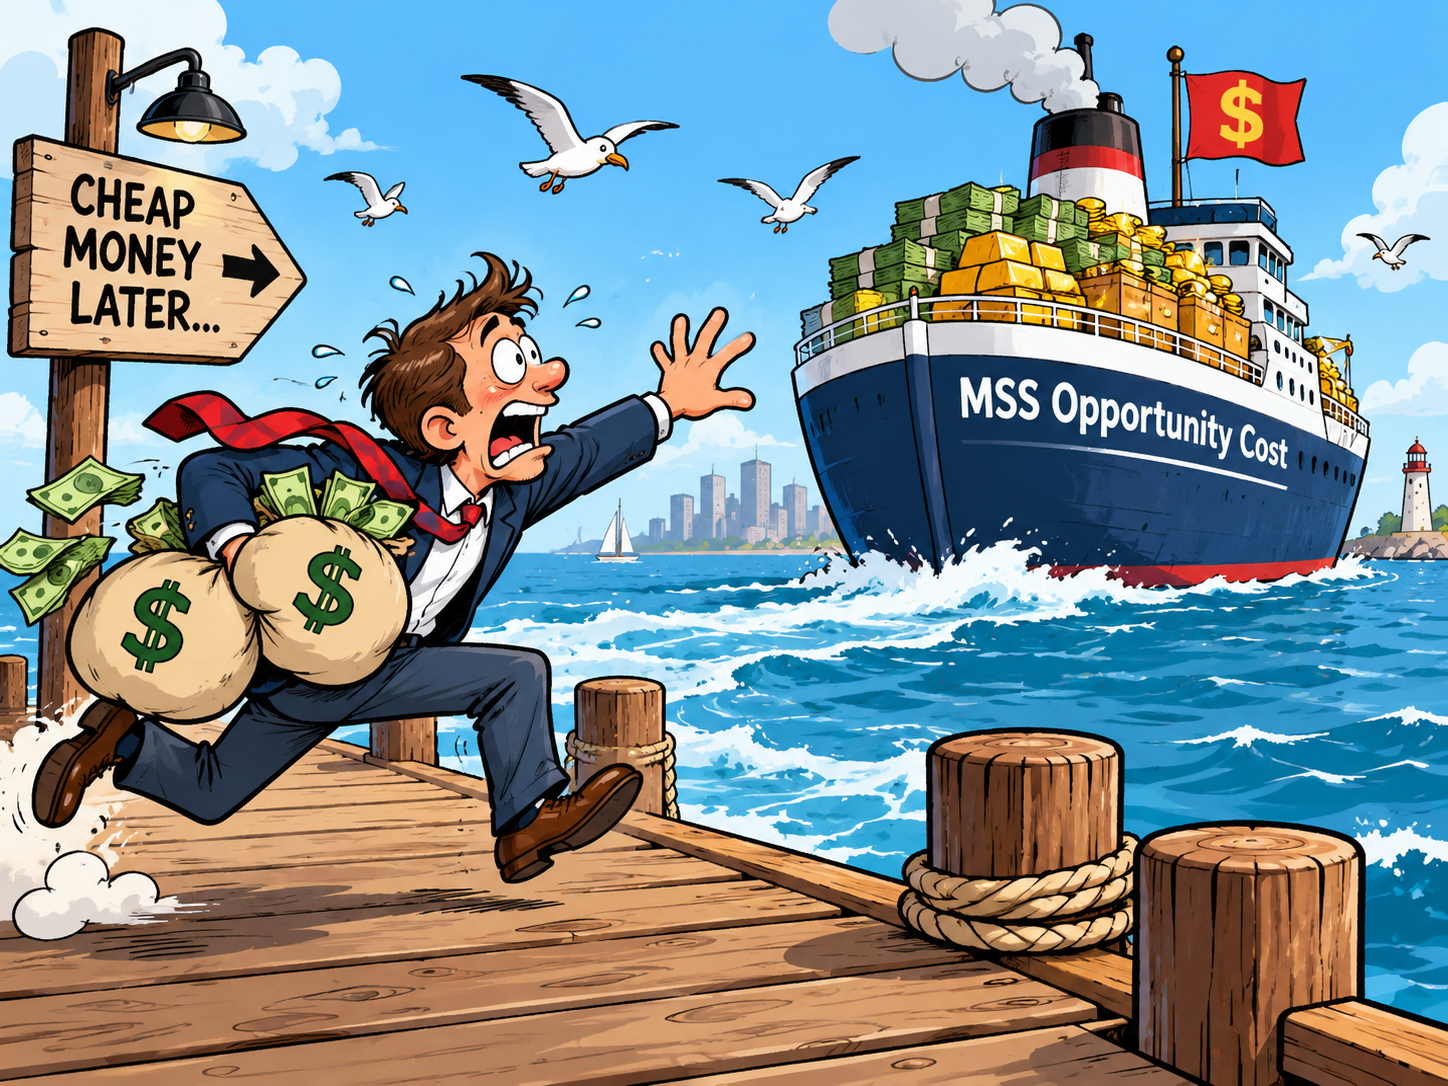
Your bank offers a terrific rate. It can also close in 45 to 60 days. Congratulations. You have the cheapest loan on a property you no longer own. That is opportunity cost.
Investors frequently step over dollars to pick up pennies because the interest rate is the easiest number on the page to compare. The better question is: What does the capital allow me to do?
David A. Wells made essentially the same point in Robinson Crusoe’s Money nearly 150 years ago. On Crusoe’s island, gold itself was economically useless because it could not be put to productive use. Money that cannot be put to work is not capital in any meaningful economic sense.
That is the question investors should ask about financing. Not simply, “What does this money cost?” but “What can this money produce?”
If short-term financing allows you to acquire an underpriced asset, fix the problem, increase the income, improve the property and ultimately refinance into cheaper permanent debt, then the bridge loan is not the investment. It is the tool that makes the investment possible.
Bridge financing should solve a problem
Private money makes the most sense when there is a clear mismatch between the property today and what that property can become. That mismatch can take several forms.
Maybe the building is physically distressed. Maybe occupancy is too low for conventional underwriting. Maybe leases need to be renewed. Maybe the borrower needs to complete construction. Maybe the property is perfectly good but the seller values certainty and speed more than squeezing out the final dollar of price. Or perhaps the collateral is strong even though the borrower’s financials do not fit a conventional lender’s box.
Ultimately, the price of money is only one line item in the economics of a deal. If higher-cost capital gives you the speed and flexibility to acquire the right asset, solve the problem, create value and refinance into permanent financing, it may be far cheaper than lower-cost money that arrives after the opportunity is gone. The better question isn’t simply, “What’s the rate?” It’s “What can this capital produce, and what does it cost me not to have it?” In investing, opportunity cost is often the most expensive cost of all.
Mark Lazar, MBA
CERTIFIED FINANCIAL PLANNER™